 Login


 Products


 Go Back to blog listing page
How a Co-Applicant Can Increase Your Home Loan Eligibility and Approval Chances


November 04, 2026
2 min
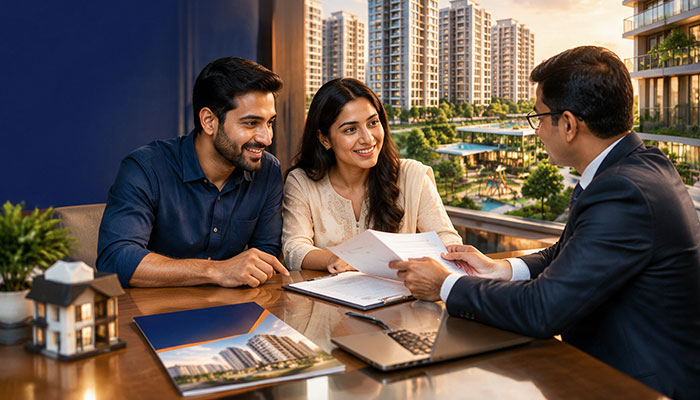
Buying a home is a big dream, but sometimes the loan amount you need is more than you can qualify for on your own. This is where a co-applicant can help. Adding a second person may strengthen the application, depending on the financial profiles of both applicants. That is why many families choose a joint home loan.
In this blog, we will explain how a co-applicant works and how it can make your home loan journey easier. We're going to keep it basic.
What Is a Co-Applicant in a Home Loan?
A co-applicant is someone who applies for a home loan with you. This person is jointly liable for repaying the loan. The lender reviews both applicants’ income, credit score and repayment ability before approving the loan.
You may also hear the terms joint applicant home loan and co-borrower home loan. They mean almost the same thing. Both people are equally responsible for repaying the loan.
Co-Applicant vs Co-Owner
There is often confusion between these two terms:
- Co-applicant: Applies for the loan and is jointly responsible for repayment.
- Co-owner: Has a legal ownership share in the property.
A co-owner is usually also a co-applicant, but a co-applicant does not always have to be a co-owner. Check the lender’s rules for this.
Who Can Be a Co-Applicant?
Co-applicant eligibility depends on the lender, but these people are usually accepted:
- Spouse
- Parents
- Siblings
- Adult children
For a home loan with spouse, the process is very common and simple. Lenders also like close family members because they often live in the same home and share the same goals.
The co-applicant must have a stable income, a good credit score and valid documents. Some lenders may also have age requirements.
Co-Applicant Home Loan Benefits
There are many co-applicant home loan benefits. Let’s look at the main ones.
1. Higher Loan Eligibility
This is the biggest advantage. Lenders add both applicants’ incomes to decide how much loan you can get. So a home loan with co applicant usually gives you a larger loan amount than a single application.
If your income alone makes you eligible for a ₹30 lakh loan, adding a co-applicant with a similar income could help you get a much higher amount. The exact amount depends on the lender’s policies and your financial profile.
This is the easiest way to increase home loan eligibility without waiting for a pay hike.
2. Better Chances of Approval
Lenders assess the combined financial profile and repayment capacity of both applicants. If one applicant has a low income or a short job history, the other applicant’s strong profile can balance it out. This may support loan eligibility, subject to the lender's assessment.
3. Tax Benefits for Both Applicants
Under applicable Income Tax provisions, each applicant who is both a co-borrower and a co-owner of the property may be eligible to claim tax deductions on their share of principal and interest payments, subject to prevailing tax laws and eligibility conditions.
4. Lower Burden on One Person
The Equated Monthly Instalment (EMI) can be divided between both applicants. This makes monthly payments more manageable and leaves room in your budget for other needs.
5. Possible Interest Rate Benefits
Some lenders give special rates or concessions if a woman is a co-applicant or co-owner. These offers vary, so confirm the current details with your lender.
6. Stamp Duty Savings
In some states, stamp duty is lower if the property is registered in a woman’s name. Adding your wife, mother or sister as a co-owner may save you money. Rules vary by state.
How a Co-Applicant Can Increase Your Home Loan Eligibility
Lenders generally look at these things:
- Combined income: The income of both applicants is considered.
- Credit score: A good co-applicant score can strengthen the application.
- Existing loans: Lower existing EMIs leave more room for a new loan.
- Job stability: A stable job or business record builds confidence.
- Age: A younger co-applicant may help you qualify for a longer loan tenure.
When both profiles are strong, the lender is more confident about approving a higher loan amount.
Things to Know Before Adding a Co-Applicant
A joint home loan has many benefits, but it is also a shared responsibility. Here are some points to remember:
- Both are equally responsible: If one person misses an EMI, both credit scores are affected.
- Credit score matters: A low score of the co-applicant can affect your chances. Check both scores before you apply.
- Choose someone you trust: Pick a person you can talk to openly about money.
- Understand the long-term commitment: A home loan term can be 15 to 20 years or more. Think about future plans, such as moving or changes in family circumstances.
- Keep documents ready: Both applicants must submit proof of identity, address and income.
Tips to Strengthen Your Home Loan Application
Follow these easy steps:
- Check both credit scores. Clear any pending dues first.
- Pick the right co-applicant. Choose someone with a stable income and a strong repayment history.
- Reduce existing debts. Pay off small loans or credit card bills before applying.
- Keep your documents in order. Salary slips, bank statements, ID proofs and tax returns should be up to date.
- Borrow only what you need. A lower loan amount means a lower EMI and a better chance of approval.
- Compare lenders. Check interest rates, fees and repayment options before you decide.
Conclusion
Adding a co-applicant can be an effective way to strengthen your home loan application. It can raise your eligibility, improve your chances of approval, reduce the EMI burden and may even bring tax and stamp duty benefits. By applying with your spouse, parent or sibling, you can get closer to your dream home.
Individuals planning to purchase a home may explore home loan options from IIFL Home Loans and review the applicable eligibility criteria, documentation requirements, interest rates, fees and terms before applying.
Tags

Most Read Blogs

Frequently Asked Questions (FAQ’s)
Will adding a co-applicant improve my home loan eligibility?
Ans:
Yes. Lenders consider both applicants’ incomes, which may help you qualify for a larger loan. The exact amount depends on your income, credit score and existing loans.
Who is eligible to be a co-applicant for a home loan?
Ans:
A co-applicant is usually a spouse, parent, sibling or adult child. Each lender has different rules, so check with your lender for the exact co-applicant eligibility.
Does the co-applicant have to be a co-owner of the property?
Ans:
Not always. Some lenders allow a co-applicant who is not a co-owner, while others require co-applicants to be co-owners. Check this with your lender.
What happens if the co-applicant has a low credit score?
Ans:
A low credit score can affect your loan approval and interest rate. It is better to check both credit scores before you apply and improve them if needed.
Can I get a home loan with my spouse?
Ans:
Yes. A home loan with a spouse is very common. Both incomes are considered, which can increase your eligibility. If you co-own the property, both of you can also claim tax benefits.
What can we help you with?

Home Loan

Secured Business Loan

Balance Transfer

Home Improvement Loan

Home Loan for Uniformed Services

NRI Home Loan
Home Loan
Secured Business Loan
Balance Transfer
Home Improvement Loan
Home Loan for Uniformed Services
Get instant support with existing loan related queries

Raise a Request Get instant access to your existing Loan Account with us Raise a Ticket 

Call Helpline Speak with our Customer Support Executive on 1860 267 4999

Visit Nearby Branch You can walk into any of our 300+ branches, spanning across 18 states Get Directions
Our Brands & Subsidiaries
Insurance Partners


HDFC Life Insurance Learn more
Bajaj Life Insurance Learn more
ICICI Prudential Life Insurance Learn more
Go Digit General Insurance Learn more
Aditya Birla Capital Insurance Learn more
Bajaj General Insurance Learn more


